A term plan pays your family when you die. Fine. But what if you fall seriously ill and live? The bills still arrive. A heart attack or cancer can cost lakhs, and you may not earn for months.
That’s why many buyers add critical illness cover to a ₹1 crore term plan. Sounds simple, right? It isn’t. The diseases named, the waiting time and the payout rules change from plan to plan. So check the fine print first, then pay. Here’s what to look at.
Why the Illness List Comes First
Every cover comes with a critical illness list. Only the diseases on that list get paid. Your illness isn’t named? You get nothing, even if it’s serious.
So the list matters more than the cover amount. Some plans name around 20 illnesses. Others name 60 or more. A short list leaves big gaps.
IRDAI has set standard meanings for many common illnesses, so the wording is more even now. Still, read it line by line. Ask for the full list in written form. A sales call is not proof, and a promise on the phone means nothing later.
Check 1: Are the Common Illnesses Covered?
Start with the big ones. Most plans cover them, but the fine print is where plans differ.
| Illness | What to Ask |
| Cancer | Are early stages covered, or only advanced ones? |
| Heart attack | Is a mild attack covered? |
| Stroke | Does it need lasting damage? |
| Kidney failure | Is regular dialysis needed to claim? |
| Organ transplant | Which organs are named? |
| Paralysis | How long must it last? |
Take cancer. Some plans pay in full only for late stage cancer. Early stage gets a small part, or nothing. That one detail can change a claim by lakhs. Ask the insurer to show it in writing.
Also check newer illnesses like Alzheimer’s and Parkinson’s. Some lists skip them.
Check 2: Rider or Separate Cover?
A rider is an add-on to your term plan. It usually costs less than a separate policy. But it has limits.
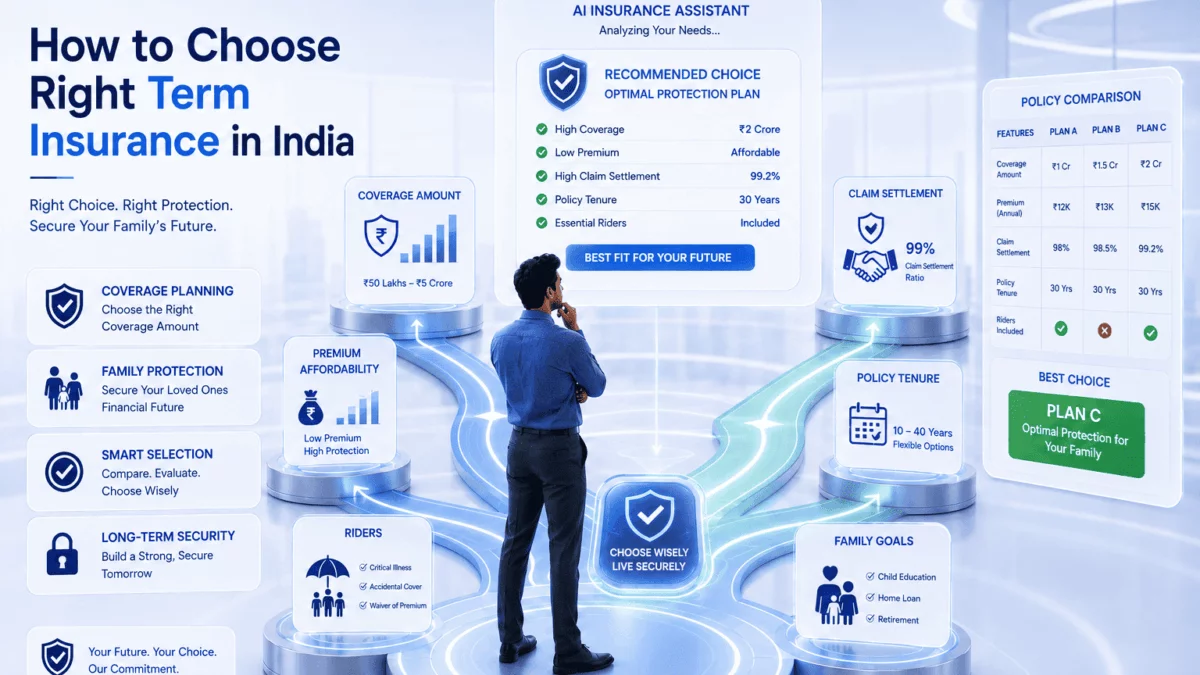
So when you hunt for the best term insurance plan for 1 crore, check how much rider cover it allows. A rider on a ₹1 crore plan may give only ₹10 lakh to ₹25 lakh.
| Option | Good Side | Watch Out |
| Rider | Lower cost, one policy | Cover is often smaller than the term sum |
| Separate plan | Higher cover, own terms | Costs more, one more policy to track |
Neither is always better. If your budget is a little bit tight, then a rider will be a good start for you. If your family has a history of illness, a separate plan may be safer.
Check 3: How Does the Payout Work?
Here’s what usually happens after a diagnosis:
- Lump sum: The full amount comes at once. Spend it on anything.
- Survival period: Many plans pay only if you live 30 days after diagnosis.
- Waiting period: Many plans skip illness found in the first 90 days.
- Base cover: Does your ₹1 crore stay whole after a payout? Some plans cut it.
Here’s an example with made-up numbers. You have a ₹1 crore term plan and a ₹20 lakh rider. Cancer is found. You get ₹20 lakh. In a well built plan, your ₹1 crore still protects your family. Always ask this one before you sign.
Check 4: What Is Not Covered?
Every plan has exclusions. Read them slowly.
- Existing illness: Conditions you had before buying are often left out.
- Waiting period cases: Illness found in the first 90 days.
- Self-caused harm: Harm from drug misuse or self-injury.
- Not on the list: No payout at all.
Read this part twice. It’s where the surprises hide. Be honest on the form. Hiding diabetes or high blood pressure is the quickest way to a rejected claim. Your family pays for that mistake, not you.
Check 5: What Will It Cost?
A rider adds to your yearly premium. The older you are, the more it costs. Smokers pay more too. Here’s an example with made-up numbers for a 35 year old:
| Cover | Yearly Premium |
| ₹1 crore term plan only | ₹14,000 |
| Add ₹20 lakh rider | ₹4,500 more |
| Total | ₹18,500 |
Real prices differ by age, health and plan. Compare the extra cost with the extra cover, not just the total.
Also Read: How Term Life Insurance for Senior Citizens Differs When Choosing 5 Crore Term Insurance
Check 6: How Much Cover Do You Need?
Think of treatment cost plus lost income. Cancer care can run to ₹10 lakh to ₹30 lakh or more, and recovery can take a year. If you spend ₹50,000 a month, one year off work is ₹6 lakh by itself. Also think about EMIs. A ₹30,000 monthly home loan payment doesn’t stop because you’re in hospital. Add it all up and pick a figure that fits your case. Don’t copy a friend’s number.
Check 7: Can You Trust the Insurer?
Your family will depend on this company years from now. So check:
- Registration: Is it registered with IRDAI, India’s insurance regulator?
- Claim record: Does it settle claims fully and on time?
- Free-look period: As per IRDAI rules, you get 30 days to review the policy and cancel it.
A cheap rider from a weak insurer is no bargain. A stuck claim costs far more than a few thousand rupees saved.
A Simple Checklist
- Have I read the full illness list?
- Is early stage cancer covered?
- Do I know the waiting and survival periods?
- Does my ₹1 crore stay whole after a payout?
- Have I read the exclusions?
- Have I compared at least three plans?
- Have I been honest about my health?
Disclaimer: This article is only for general information. It is not financial, tax or insurance advice. The figures used above are only examples. Illness lists, waiting periods, premiums and policy terms change over time and differ from plan to plan. Please read the policy papers and speak to a certified financial advisor before you buy.